Published: October 18, 2026 · Last updated: October 18, 2026
TL;DR: TSMC just posted its sixth consecutive quarter of record profit, up 58% year over year, driven almost entirely by demand for the chips that power AI data centers. The world’s biggest contract chipmaker is having arguably its best run ever, right as some investors start asking how much longer that run can continue.
Numbers this good tend to speak for themselves. Taiwan Semiconductor Manufacturing Company reported a 58% jump in profit for the quarter, its sixth straight record, and the explanation hasn’t changed from the last five: everyone building AI infrastructure needs chips, and TSMC makes most of the advanced ones that matter.
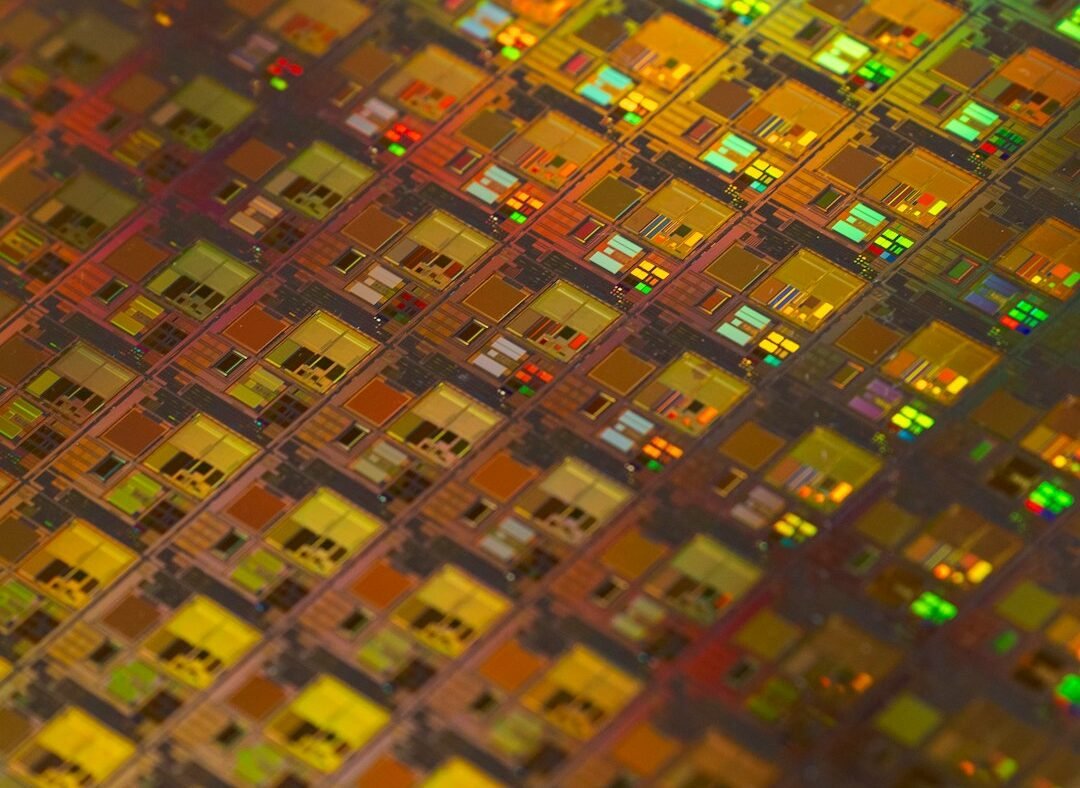
Nvidia, AMD, Apple, Google and a growing list of custom silicon shops all depend on TSMC’s fabrication capacity to actually produce the chips they design. That gives TSMC a position almost no other company in tech enjoys. It doesn’t need to win the AI race itself. It just needs everyone else to keep racing.
The demand side isn’t slowing down
TSMC’s leadership used the earnings call to reiterate that advanced chip orders, especially for the most cutting-edge process nodes, remain backlogged well into next year. That’s a notable signal in an environment where some analysts have started quietly wondering whether AI infrastructure spending is starting to outpace actual AI revenue across the industry.
TSMC’s answer to that skepticism is essentially: look at our order book, not at anyone’s spreadsheet projecting a slowdown. Capacity remains the bottleneck, not demand, and that’s been true for multiple quarters running now. The company has continued expanding its most advanced fabrication capacity, including facilities outside Taiwan, to keep pace with orders it already has in hand.
“Nobody is debating whether AI chip demand is real anymore. The debate has shifted to whether the companies buying all this capacity can monetize it fast enough to justify the spending,” said one semiconductor industry analyst reacting to the results.
The geopolitics underneath the numbers
None of this happens in a vacuum. TSMC’s dominance means its fortunes are tied directly to Taiwan’s geopolitical position, something every customer depending on its fabs has had to factor into their own supply chain planning for years now. Export restrictions, trade tensions between the US and China, and ongoing efforts by multiple governments to diversify chip manufacturing away from a single geographic chokepoint all sit in the background of every earnings call TSMC holds.
That context hasn’t slowed the stock’s performance or dented customer commitments so far. If anything, the urgency around securing guaranteed capacity has pushed major customers to lock in longer-term agreements rather than risk losing their place in the queue.
What to watch next
The real test for this run isn’t this quarter’s numbers. It’s whether the companies buying TSMC’s capacity start showing matching revenue growth from their AI products, or whether capital expenditure keeps outrunning actual returns across the industry. TSMC will keep printing strong results as long as the orders keep coming in, regardless of whether the AI economy underneath those orders is as healthy as the chip demand suggests.
Related: ASML’s earnings told a more cautious story this same week, and Cursor’s record funding round shows that same AI-driven demand showing up on the software side too.
Bottom Line: TSMC’s sixth straight record quarter is real and the order backlog backs it up, but it’s also a reminder that chip demand and AI product revenue are two different numbers. Right now the first one looks unstoppable. The second one is the one worth watching closely.
Follow Teck Hustlers: Facebook · X · Instagram · LinkedIn · TikTok · Pinterest

The Teck Hustlers Editorial Team covers technology, business, finance and gaming news for readers who want the story behind the headline. Every article is researched, written and edited by our in-house team, checked against company announcements, filings and reputable reporting, and updated when new facts emerge. We focus on what each development means for founders, professionals, investors and everyday users. Have a tip or a correction? Reach us through our contact page.